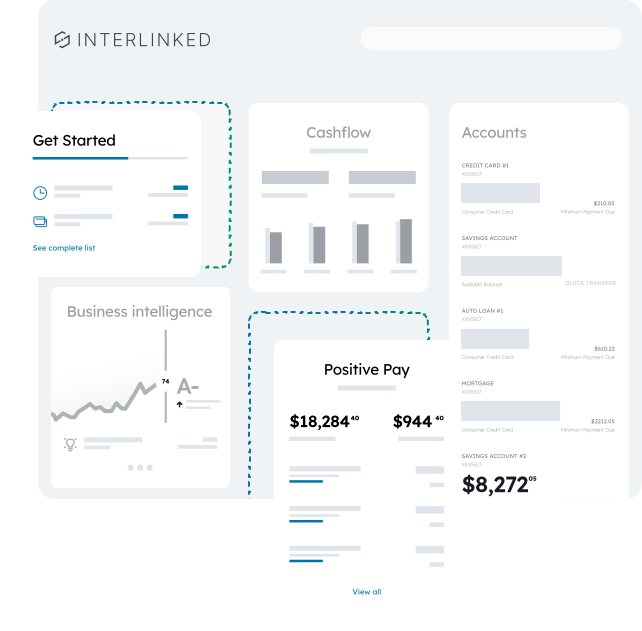
Digital banking platform for small and mid-size businesses
Small businesses need banking tools sized to their operations, not stripped-down consumer features or oversized corporate systems. Q2 gives your bank or credit union a configurable digital banking platform that matches functionality to each SMB's size and industry.
Q2's Small Business Digital Banking Platform gives banks and credit unions one configurable system that matches functionality to each SMB's size and industry. Small businesses need banking tools sized to their operations, not stripped-down consumer features or oversized corporate systems.
How does Q2 give SMBs the flexibility to bank on their terms?
If there’s one word to describe small business owners and entrepreneurs, it’s busy. They want the flexibility to do their banking the way they need to, when they need to. For instance, retail SMBs may require POS integration, while contractors need invoicing tools. With Q2, you can give any type of SMB the flexibility and scalability needed to meet its unique challenges.
Tailored experiences
With the Q2 Digital Banking Platform®, SMBs have the capabilities and functionality specific to them, and you can go further to create a custom experience based on their needs. Features such as cash flow management, multiple user roles, and account segmentation give you the ability to meet a wide range of SMB requirements.
Beyond banking
When you provide fintech solutions for services such as expense management and payroll, you strengthen relationships and keep your account holders from sourcing those solutions themselves.
Room to grow
As your SMB account holders grow, so do their banking requirements. With Q2 digital banking, you can add features and functionality on demand to meet needs.
How does Q2 personalize banking for each small business?
Make it personal
With Q2 Composable Dashboard, you can leverage the power of data insights with dynamic personalization that’s integrated into every interaction, every decision. Beyond offering the baseline services SMBs require, take it a step further by packaging those services based on specific needs.
Q2 Innovation Studio
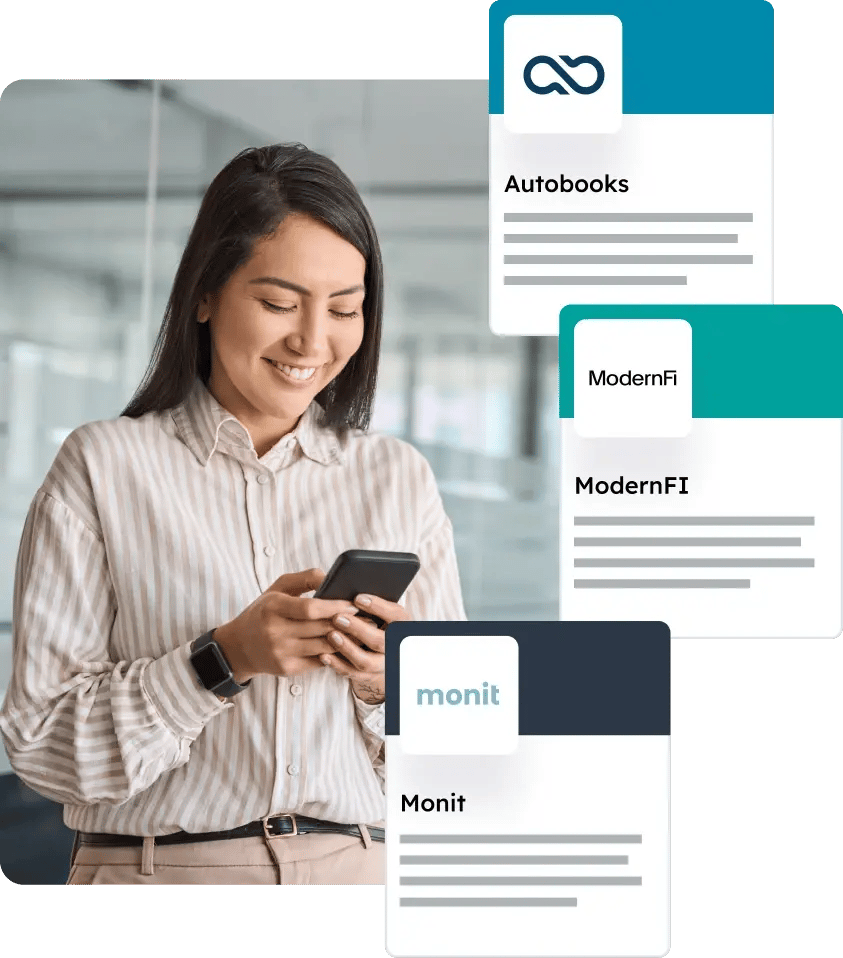
Eighty percent of small businesses prefer to get fintech solutions through their primary financial institution, according to 2025 research from Datos Insights, but most FIs aren't set up to deliver them. With the Q2 Innovation Studio fintech partner ecosystem, you can turn your digital banking platform into the operating hub small businesses rely on, with solutions that grow alongside them:
Payments — help SMBs get paid, track payments, and stay organized inside your platform, with partners like Autobooks and PayRecs
Origination & deposit growth — give SMBs fast access to capital and protect growing balances as they scale, with partners like Rapid Finance and ModernFi
Financial wellness — provide clear, real-time visibility into cash health and early risk signals, with partners like Monit
Deploying new fintech integrations also becomes a much faster and smoother process, with timelines shrinking from several months to typically just a few weeks.
Business account opening
Open accounts with ease
With business account opening powered by Prelim, you can automate the process of opening new accounts and adding accounts for small businesses, giving them autonomy with clear, easy-to-understand steps, reducing paper, and increasing processing times.
Treasury fulfillment
Get SMBs up and running on business banking solutions fast with Q2 Treasury Fulfillment, providing a streamlined, automated fulfillment process that eases communication between the front and back office.
Simplify cash flow and
financial insights
Q2 provides SMBs with simplified and intuitive dashboards for real-time cash flow tracking, as well as features like invoice management, expense alerts, and cash forecasting.
With the power of our platform on your side, you can move from “just a bank” to a true financial partner, offering actionable business insights. Embedded fintech integrations such as accounting and expense management also help support client retention.
Q2 Positive pay
Stop fraudsters in their tracks
Be an ally against fraud by equipping SMBs with Centrix Exact/TMS™, which gives them the positive pay capability to stop cyber criminals before they begin—and creates a new source of fee income for your financial institution.
Payments from A to Z: ACH, checks, and instant payments
Many SMBs struggle with managing cash flow and vendor payments. Whether it’s ACH, checks, or the instant payments rails FedNow® and RTP®, Q2 offers choice. All payment workflows can be consolidated into one platform.
Smarter customer support
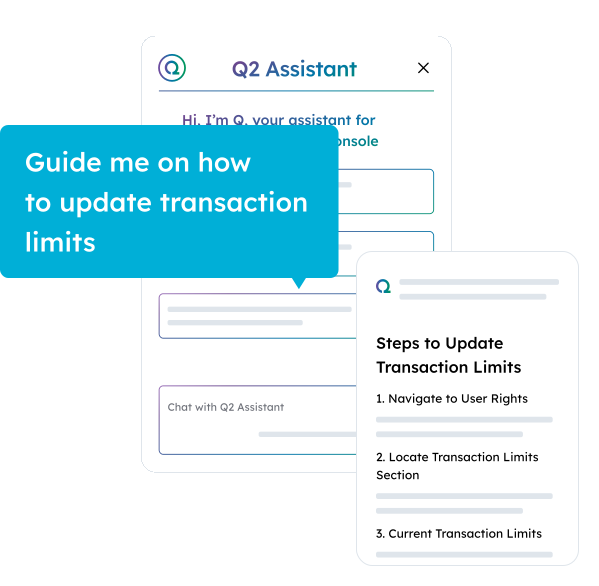
Give your support teams an AI-powered way to work more efficiently and deliver better service. The Customer Care Agent within Q2 Assistant for Digital Banking helps financial institution employees quickly find answers, resolve issues, and support account holders from within Q2 Console—helping reduce research time and create a more seamless customer experience.
Q2 earns top marks for small business banking
“The ability to more efficiently process payroll, ACH and payments; offer remote deposit capture; and deliver overall functionality has put us into a referral environment with the local CPAs. Q2 has been integral in that.”
BEST IN CLASS
Small business
"Best in Class" in Javelin Strategy and Research’s 2025 Small Business Digital Banking Vendor Scorecard
Q2 Named Market Leader in 2025 Datos Matrix: Leading U.S. Digital Small Business Banking Providers Report
Who we work with
FAQs
What is a small business digital banking platform?
A small business digital banking platform is the online and mobile banking system a bank or credit union uses to serve small business account holders, with tools like cash flow management, multiple user roles, and account segmentation. Q2's platform lets financial institutions match that functionality to each SMB's size and industry instead of offering one fixed package.
How is small business digital banking different from consumer or commercial banking?
Small businesses need more than consumer banking features but less than a full corporate treasury system. Q2 sizes functionality to the business so a retail SMB can get POS integration while a contractor gets invoicing tools, and capabilities can be added on demand as the business grows.
How does Q2 tailor digital banking to different types of small businesses?
Q2 packages capabilities by SMB size and industry, and the Q2 Composable Dashboard personalizes each interaction using data insights. Financial institutions can configure user roles, account segmentation, and cash flow tools for individual account holders.
What payment options can banks offer small businesses through Q2?
Q2 supports ACH, checks, and instant payments over FedNow and RTP, consolidated into a single platform. SMBs can also accept and track payments through Q2 Innovation Studio partners such as Autobooks and PayRecs.
How quickly can a financial institution add new fintech integrations?
Through Q2 Innovation Studio, new fintech integrations typically go live in a few weeks rather than several months. The partner ecosystem spans payments, origination and deposit growth, and financial wellness tools.